
Self Assessment deadline: what to get ready
The 2025/26 return is due by 31 January 2027. The dates, the paperwork to gather now, payments on account and why November beats January.
Short, practical notes on the rules and deadlines that affect owner-managed businesses. No jargon, no padding, and nothing published for the sake of publishing.
The 2025/26 return is due by 31 January 2027. The dates, the paperwork to gather now, payments on account and why November beats January.
Every director and person with significant control must verify with Companies House this year. Who, how, and what happens if you miss it.
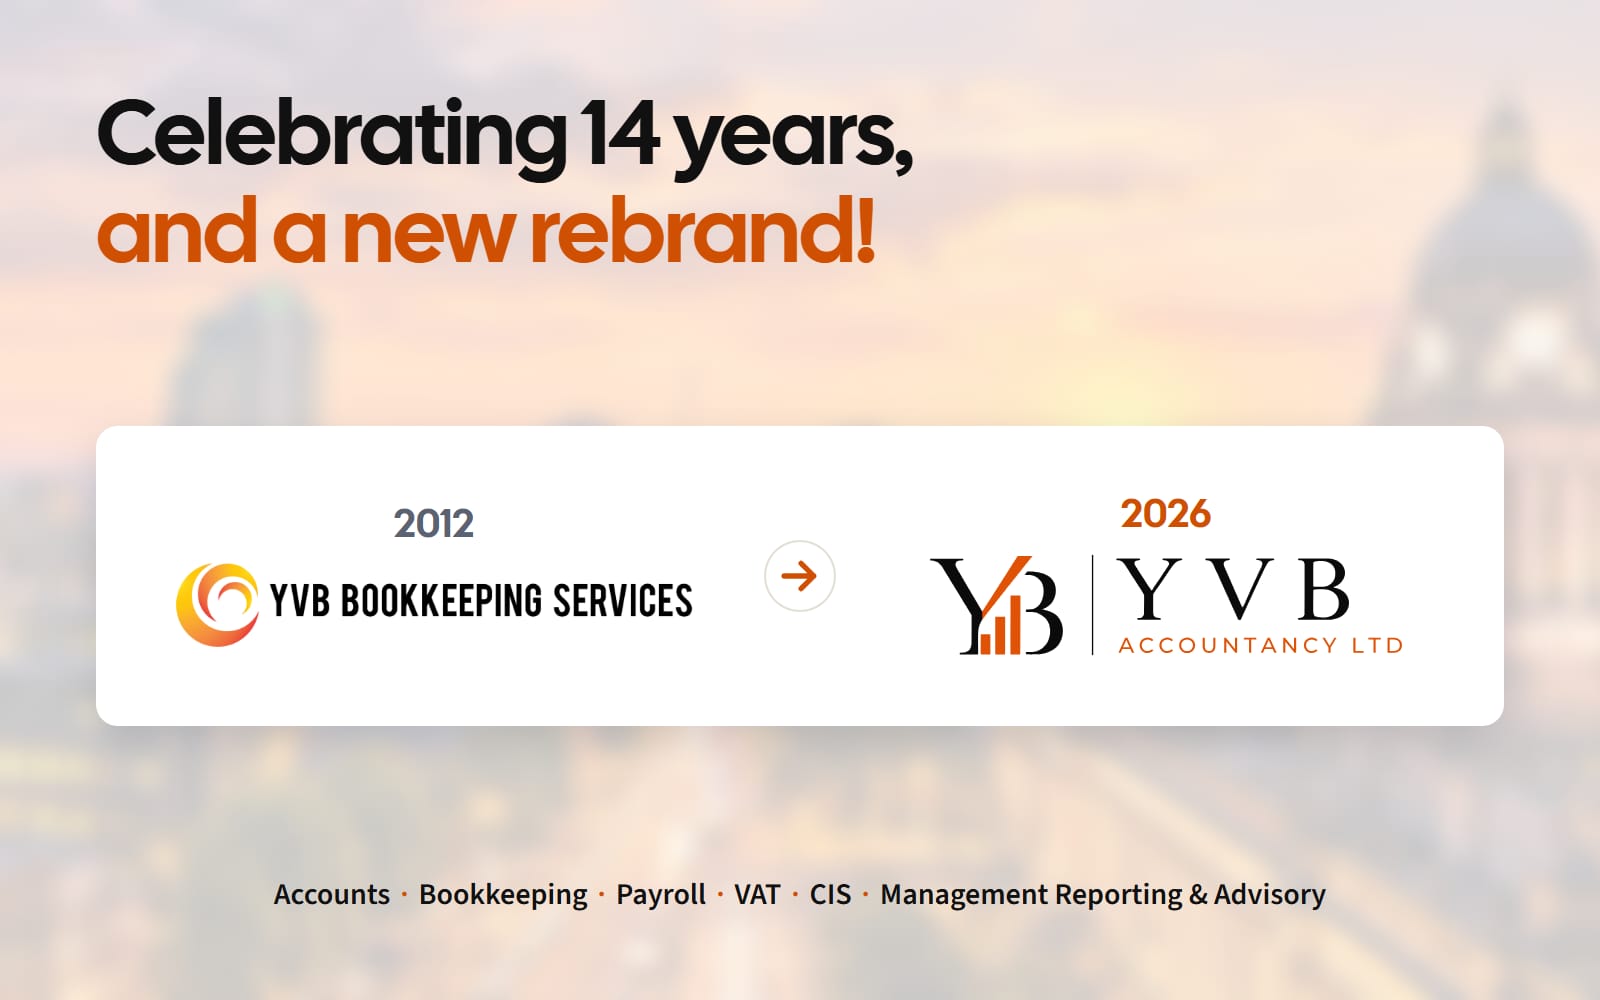
YVB Bookkeeping Services is now YVB Accountancy. Why the name changed, what has not, and a thank-you to the clients who made fourteen years possible.
Live since April 2026 for sole traders and landlords over £50,000. The four deadlines, what each update contains and the penalty points.
How the balance goes overdrawn without anyone deciding, the Section 455 charge and nine-month rule, and the habits that keep it clean.
Employer's NI at 15% above £5,000, the £10,500 Employment Allowance and a worked example of the true cost of a hire.
How director-shareholders take money out, the rules that make dividends lawful, and the mistakes that cause real trouble.
The three pricing models, what actually drives your fee, and why the cheapest quote is rarely the cheapest accountant.
Professional clearance, records handover and HMRC authorisations: what actually happens, what it costs and when to do it.
Invoice faster, chase properly, set tax aside and forecast. The levers that decide whether you can pay wages on Friday.
The checklist your accounts preparer needs, the deadlines that follow a year-end, and why the first month is the cheapest time to do it.
When turnover approaches £90,000 the clock starts ticking. How the rolling twelve-month test works and why timing your registration matters.
Late registration, blocked reclaims, missed reclaims, scheme misfits and returns that do not reconcile. The expensive classics.
Who MTD already covers, how the Income Tax rollout works, and why well-kept records make the whole subject a non-event.
The wholly-and-exclusively rule, the categories most businesses can claim, and the traps that invite an HMRC enquiry.
Liability, tax, admin and credibility: the real trade-offs behind the first structural decision every business faces.
Structure, registration, bank accounts, records and the tax habit that prevents the January panic. The practical steps, in the right order.
Registering as an employer, payroll and RTI, pension duties, minimum wage and the insurance the law requires from day one.
All three keep compliant books and file MTD returns. Where they differ, and how to choose based on your business rather than habit.
Receipts and payments versus SORP accruals, the independent examination and audit thresholds, the annual return and fund accounting.
Verification, deductions, statements and the monthly return. The routine that keeps construction contractors on the right side of HMRC.
Who accounts for VAT in construction chains, what invoices must say, and the cash flow effect on subcontractors.
New limited company? HMRC expects to hear from you within three months of starting to trade. What counts as trading, and what happens next.
Every company must file one yearly, it contains no accounts, and missing it can end in strike-off. The annual filing explained.
Revenue, margins and the layers between them. How to read the account in ten minutes, and why profit is not cash.
The records the law requires, the six-year rule, and why photographing receipts as you go beats every other system.
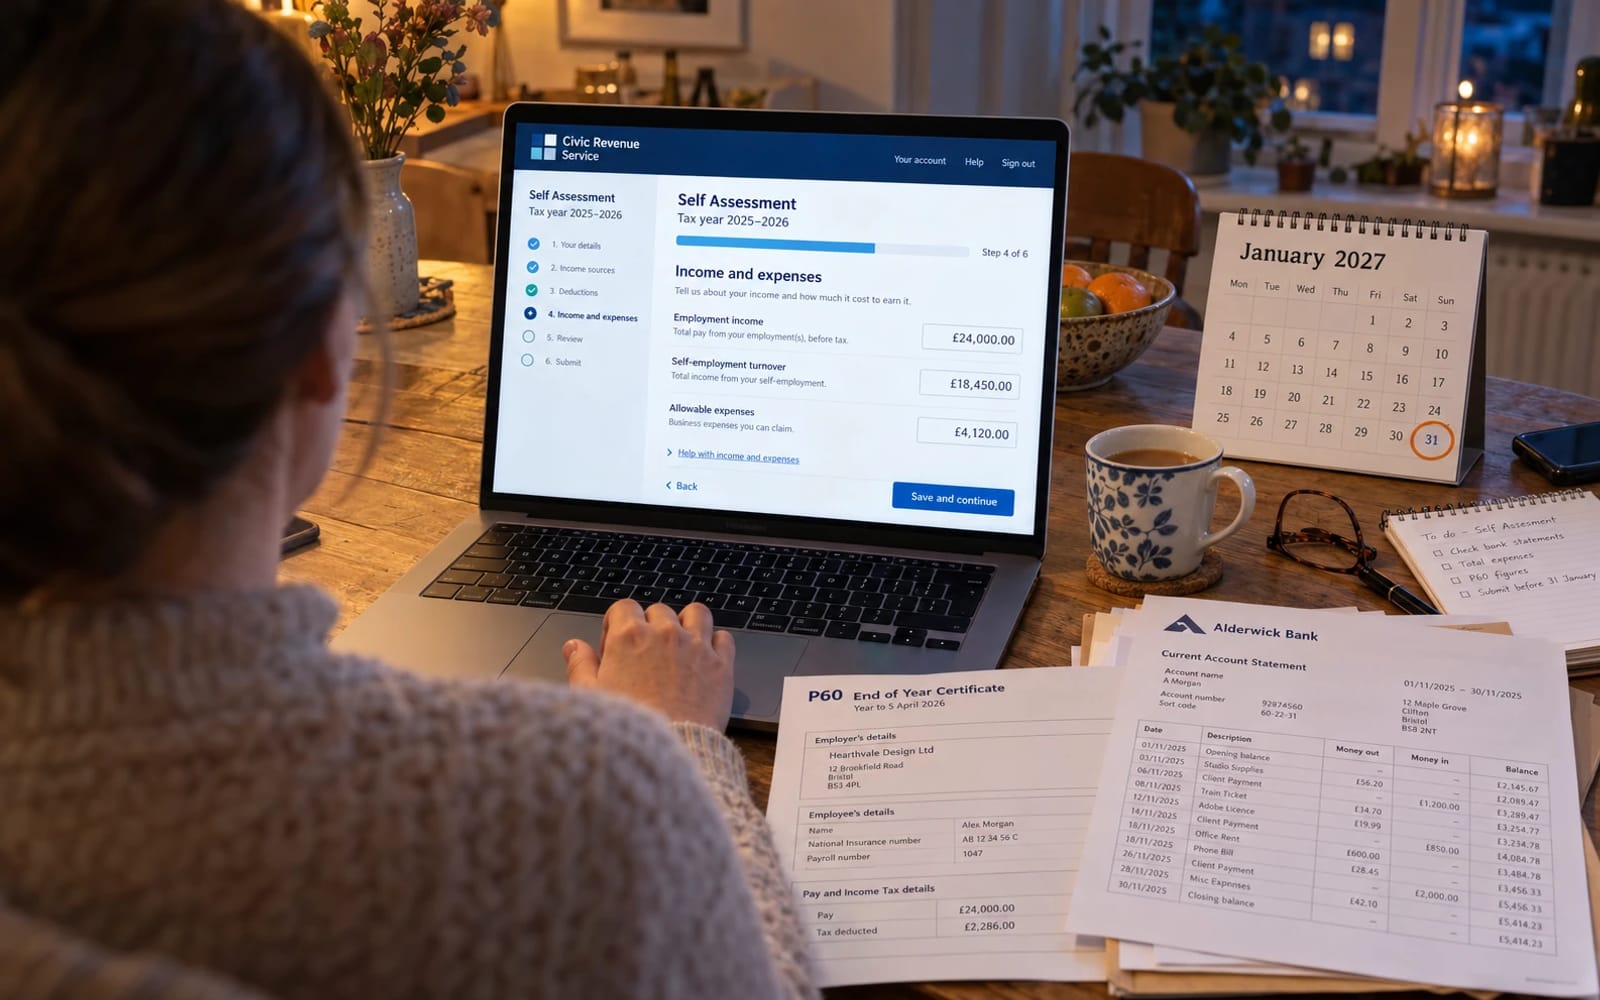
Who has to file a tax return, the deadlines that matter, and the payments-on-account surprise that catches first-timers.
For questions about how any of this applies to your business, get in touch; guidance on this page is general and is not a substitute for advice on your specific circumstances.